A Consumer Law Firm
We Sue Credit Bureaus for Credit Report Errors
If an error on your credit report cost you a loan, a job, an apartment, or your peace of mind, federal law may give you a claim. Our law firm represents consumers nationwide from our office in Baton Rouge. You pay nothing out of pocket, and nothing at all unless we win.

29+
years of combined experience
800+
consumers represented
50 States
Federal courts nationwide
$0
No fee unless we win
Raburn Kaufman is a consumer law firm in Baton Rouge, Louisiana that works throughout the United States to represent people suing the credit bureaus, lenders, and background check companies under the Fair Credit Reporting Act (FCRA), a federal law. We handle credit report error cases only, we file only in federal court, and our clients pay nothing out of pocket.
We Are a Law Firm, Not a Credit Repair Company
Credit repair companies send letters. We file lawsuits.
That distinction matters, because it changes what we can and cannot do for you. We do not promise to clean up your report, raise your score, or make accurate information disappear. What we do is hold credit bureaus, lenders, and screening companies accountable when they break federal law.
We litigate FCRA claims in federal court only. We handle no cases in state court, and we never defend these cases. We represent consumers, and only consumers.
If you are looking for someone to improve your credit profile, we are not the right firm, and we will say so on the first call.

Who We Can Help, and Who We Cannot
We do one thing. Being clear about it saves you time, and it means the people we do take on get our full attention.

We Handle
01
Inaccurate, Incomplete, or Unverifiable Information on a Credit Report
Wrong information can follow you for years. Federal law gives you the right to challenge it and have it corrected.
02
Errors on Background Checks, Employment Screening Reports, and Tenant Screening Reports
Screening companies sell reports about you to employers and landlords. The same federal law applies when they get it wrong.
03
Disputes the Credit Bureaus Ignored, Closed, or Rubber-Stamped as Verified
A bureau has to run a reasonable reinvestigation. A form letter that says verified is not the same as doing the work.
04
Fraudulent Accounts from Identity Theft That Survived a Dispute
You reported the fraud and you disputed the accounts. If they are still on your file, you have options.
05
Credit Pulls Made Without a Legal Reason
A company needs a permissible purpose, meaning a legal reason, before it looks at your credit. Curiosity is not one.

We Do Not Handle
01
Credit Repair and Raise Your Credit Score
We do not do credit repair, and we cannot promise a score. We enforce your rights when a report is wrong, and correcting inaccurate items, especially derogatory ones, can often help your credit.
02
Removing Information That Is Accurate, Even If It Is Hurting You
If the record is true, it stays. Our work is limited to information that is inaccurate, incomplete, or unverifiable.
03
Credit Repair of Any Kind
We are a law firm, not a credit repair company. Those are two different businesses under two different laws.
04
Bankruptcy, Repossession, Personal Injury, or General Civil Litigation
We only deal with a bankruptcy or repossession if they are inaccurately reported on your credit.
05
Free Legal Advice over the Phone
The free review is a real look at your documents, not a quick answer to a general question.
Services
FCRA and consumer-reporting cases we take to federal court. If one matches your situation, it may be a case.
Browse All Services- 01Identity Theft
As experienced identity theft attorneys, we will help you reclaim your identity and restore your credit reputation.
- 02Mixed Credit Files
File mixing occurs when one consumer's credit information is placed on another consumer's credit file. Contact us to discuss your options.
- 03Deceased Reporting Errors
Have you been marked as deceased on your credit report? Our attorneys can help.
- 04Background Check Errors
Unfortunately, sometimes errors in your credit report can lead to you losing out on a job opportunity or being fired from a job. We can help you navigate through this.
- 05Credit Reporting Attorneys
Are there errors on your credit reports? You may be entitled to financial compensation. Our experienced credit attorneys can help.
- 06Inaccurate Judgment Reporting Errors
Is your credit report showing an inaccurate judgement in your name? You may be entitled to financial compensation.
- 07Zombie Debts
Are old accounts still appearing on your credit? When dealing with these "zombie debts," legal counsel is often needed.
- 08Failure to Report 1099-C Cancellation of Debt
If a creditor fails to issue a 1099-C, it can negatively affect your credit score. Our experienced attorneys can help.
- 09Duplicate Debt Reporting Errors
Is a single account reporting more than once on your credit report? Our experienced credit reporting attorneys can help.
- 10Inaccurate Bankruptcy Reporting
Are bankruptcy-related credit reporting errors affecting your credit? Our attorneys can help.
- 11Inaccurate Under Age Debt Reporting Errors
Is a debt appearing on your credit report related to an account that was opened before you turned 18? Our attorneys can help.
- 12Unauthorized Credit Pulls
Unauthorized inquiries on your credit report can negatively impact your credit score. Our experienced credit reporting attorneys can help.
- 13RideShare Background Check Errors
Have you lost out on a job with Uber or Lyft due to an inaccurate background check report? You may be entitled to financial compensation.
- 14Food Delivery Background Check Errors
Have you lost out on a job with UberEats, Doordash, or others due to an inaccurate background check report? You may be entitled to damages.
- 15Tenant Screening Reporting Errors
Facing tenant screening reporting errors? Count on Raburn Kaufman for expert legal guidance to rectify inaccuracies and protect your rental prospects.
How a Case Works
Most people have never sued anyone. Here is the whole process, start to finish.
Free Review
You send us your credit reports, your dispute letters, and any denial letters you received. We read them and tell you whether you have a claim under the FCRA.
We Build the Claim
We identify who reported the error, what they were required to do, and what they failed to do. Your paperwork is the evidence, which is why we ask you to keep everything.
We File in Federal Court
Your case goes to a United States district court. If one of our attorneys is not licensed in your area, we retain local counsel for you at no extra cost.
Resolution
Most FCRA cases resolve without a trial. We keep you informed at every stage, and you decide whether to accept any offer.
You will not be handed off to a call center. You will work with Jonathan, Kyle, and our staff.
You do not pay unless we win
You will never write us a check out of your own pocket. If we take your case and we do not win, you owe us nothing.
The FCRA is built this way on purpose. When a consumer brings a successful action, the law allows recovery of costs and reasonable attorney fees from the company that broke the law. That is how we get paid, which means the fee comes from the case rather than from you.
What you recover depends on the facts of your case, what the record shows, and whether the violation was willful or negligent. We will not put a number in front of you before we have read your file, and no honest firm would.
What Clients Say
Watch Our Clients
All Client Videos
Prior results do not guarantee a similar outcome. Every case is different and must be evaluated on its own facts.
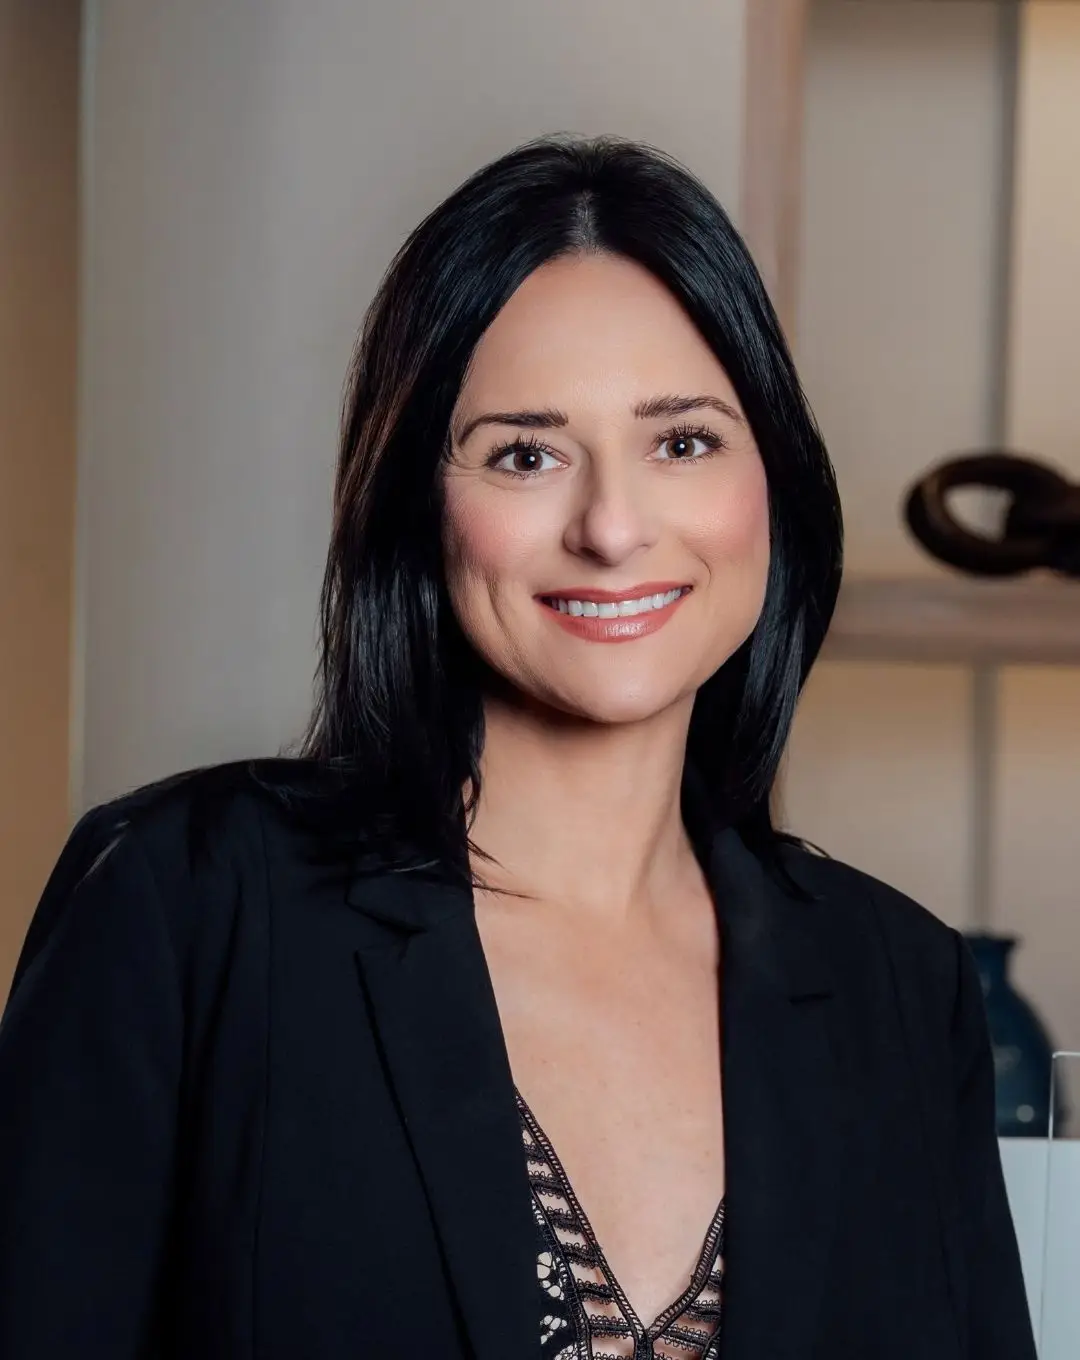
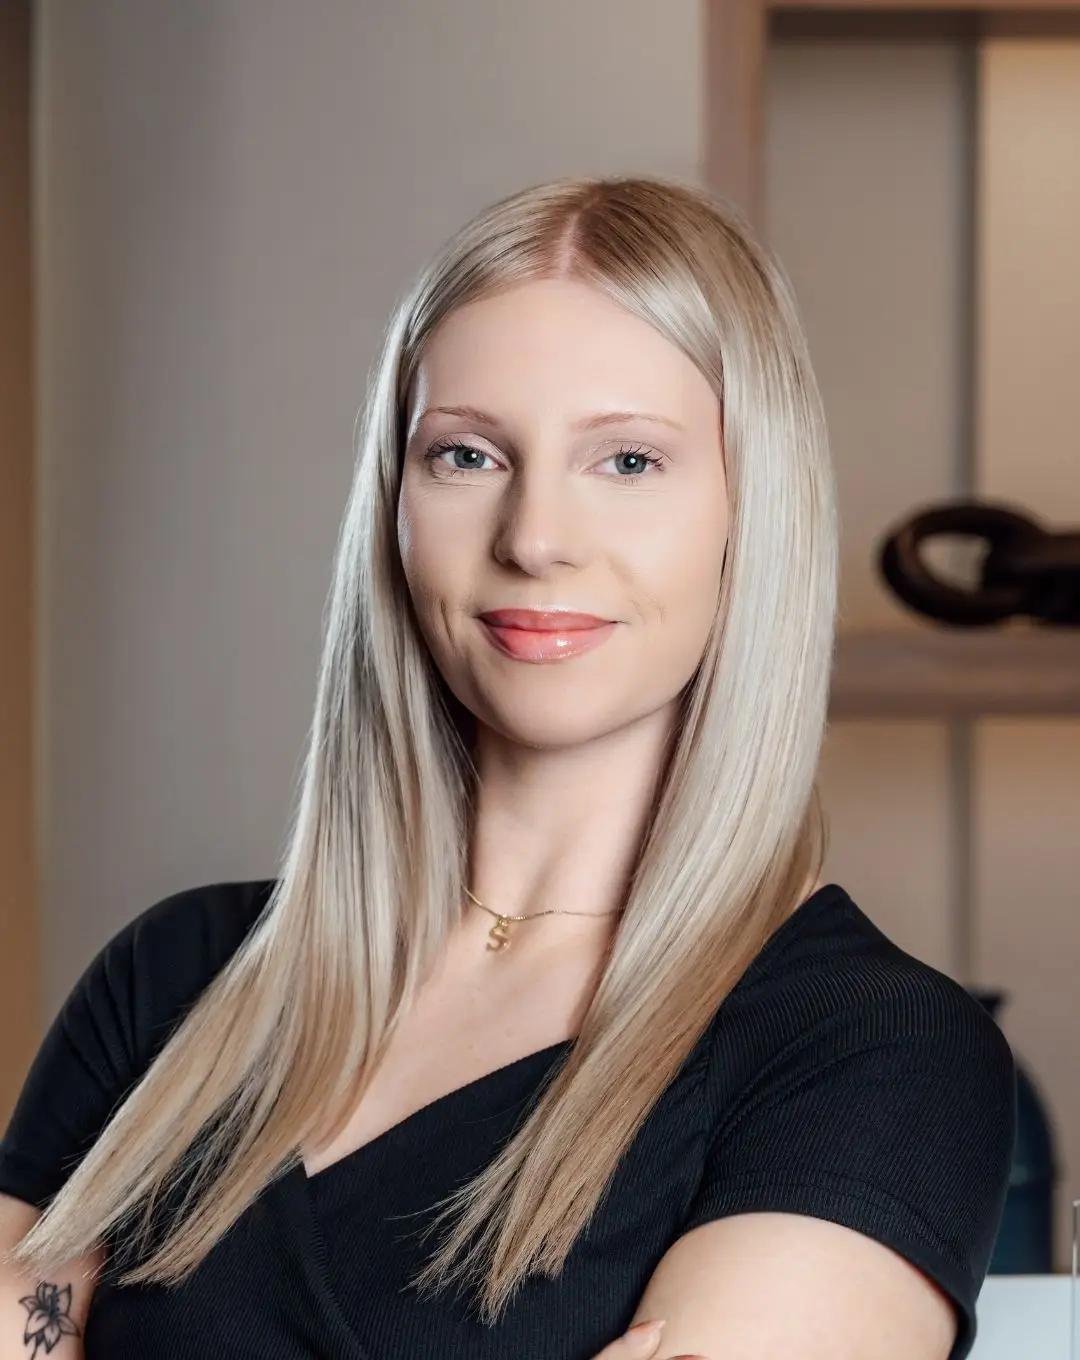
Meet the Attorneys
Between them, Jonathan and Kyle have spent their careers on one side of these cases: the consumer’s.
Representing Consumers Nationwide
Our office is in Baton Rouge, and we handle credit reporting cases for consumers nationwide. Because the FCRA is a federal law, these cases belong in federal court no matter where you live, so you do not need a lawyer down the street. You need one who files these cases.
For clients in Louisiana, we file in the federal district courts here, and we regularly work with consumers in Baton Rouge, New Orleans, Shreveport, and Lafayette. For clients elsewhere, we file in the district court that covers you, and we bring in local counsel when we need to at no extra cost to you. Every potential case still depends on its facts, dispute history, and jurisdiction.
Federal judicial districts
94courts. Yours is one of them.
Middle District of Louisiana — our home court, in the Fifth Circuit.

Where we file
- M.D. La.Home
- Baton Rouge
- E.D. La.
- New Orleans
- W.D. La.
- Shreveport · Lafayette
- Every other district
- Wherever you live
Where a court requires a lawyer admitted there, we retain local counsel for you — at no extra cost, and we stay on the case.
Frequently Asked Questions
Can I sue a credit bureau for reporting wrong information?
Yes. The FCRA lets you bring an action in federal court when a credit bureau or the company that furnished the information fails to follow the law. The most common claims involve a bureau that did not run a reasonable reinvestigation after a dispute, or that kept reporting information it could not verify.
How much does an FCRA lawyer cost?
Nothing out of your pocket. When a consumer brings a successful FCRA action, the law allows recovery of costs and reasonable attorney fees from the company that violated it. If we take your case and do not win, you owe us nothing.
How long do I have to file?
Under federal law, the deadline is the earlier of two years after you discover the violation or five years after the violation happened. That is sooner than most people expect, and the discovery date is often disputed, so it is worth having someone look at your dates early.
How long does a credit bureau have to investigate my dispute?
Generally 30 days from the day it receives your dispute. If you send additional relevant information while the investigation is open, the bureau can extend that to 45 days. Once it finishes, it has five business days to send you the results in writing.
The bureau said my dispute was "verified." Is that the end of it?
No. A verified response does not mean the bureau did what the law requires. The FCRA calls for a reasonable reinvestigation. If the bureau rubber-stamped your dispute without engaging with the documents you sent, that response may itself be evidence of a violation. Keep the letter.
Do you handle cases outside Louisiana?
Yes. We represent consumers nationwide and file in federal district courts across the country. If one of our attorneys is not licensed in your area, we retain local counsel for you at no extra cost.
Can you remove accurate negative information or raise my credit score?
No. We are a law firm, not a credit repair company. We enforce your rights when information on your report is inaccurate, incomplete, or unverifiable. If the item hurting you is accurate, we cannot help, and we will tell you that during the free review.
From the Blog
Credit Report Errors
Why Credit Karma Isn't Enough: What You're Missing on Your Credit Report
Nearly 130 million Americans use Credit Karma to monitor their credit scores. The app offers convenience and free access, but it only shows part of the picture.
Read Article
Credit Report Errors
Why Using AI Tools for Your FCRA Case Is a Costly Mistake
Consumers increasingly turn to artificial intelligence for answers to complex problems, and legal issues are no exception.
Read Article
Credit Report Errors
Preparing for a Mortgage? Watch Out for Credit Errors
A credit report error can stall a mortgage application. Learn which errors to look for before you apply and how to dispute them under the FCRA before closing.
Read Article