Mixed Credit Files
Is Your Credit File Mixed With Someone Else’s?
When a credit bureau puts another person’s accounts, addresses, or numbers in your file, you can be turned down for a loan, a job, or a home over a history that is not yours. Getting it corrected on your own can be slow and frustrating. If a bureau or a company keeps reporting the errors after you dispute, federal law may give you a claim. Our attorneys review your case for free.
- Free, confidential case review
- You pay nothing unless we win
- Clients in all 50 states


4.9 on Google, 33 reviews
We are a law firm, not a credit repair company.
Get Your Free Case Review
Three quick questions. An attorney will review your answers.
Thank You for Clarifying
Raburn Kaufman handles cases involving inaccurate or unauthorized information on credit and background reports. We don’t provide credit repair, credit-score improvement, debt-consolidation, or loan-approval services, so we may not be the right firm for your current needs.
If you’re looking for help managing debt or building a budget, the CFPB explains how credit counseling works.
29+
years of combined experience
800+
consumers represented
Lawyers of Distinction2022, 2023, and 2026
We Are a Law Firm, Not a Credit Repair Company
Credit repair companies send letters. We file lawsuits.
That distinction matters, because it changes what we can and cannot do for you. We do not promise to clean up your report, raise your score, or make accurate information disappear. What we do is hold credit bureaus, lenders, and screening companies accountable when they break federal law.
We litigate FCRA claims in federal court only. We handle no cases in state court, and we never defend these cases. We represent consumers, and only consumers.
If you are looking for someone to improve your credit profile, we are not the right firm, and we will say so on the first call.

We handle claims involving
Raburn Kaufman is not affiliated with Equifax, Experian, or TransUnion.
What to Look For
Signs Your File Is Mixed With Someone Else’s
A mixed file happens when a credit bureau matches another person’s information to your file, often because of a similar name or other identifying details. It can happen even if you did nothing wrong. Check all three of your credit reports, because each bureau keeps its own file and can show things the others do not.
Accounts That Are Not Yours
Credit cards, loans, or collections that belong to another person.
Names and Addresses You Never Used
Other names, addresses, or employers, or a Social Security number or birth date that is not yours.
Calls About Someone Else’s Debt
Someone is chasing you for a balance that is not yours.
Applications You Never Made
Credit applications or denials on your report that you know nothing about.
Sudden Denials
A loan, an apartment, or a job turned down when you expected a yes.
Errors That Will Not Go Away
You disputed them and the bureau still reports them, sometimes after replying that they were verified.
Your Rights
What the Fair Credit Reporting Act Gives You
The FCRA is a federal law. It sets rules for credit bureaus and for the companies that send them information about you, so your file should hold your information and no one else’s.
This is general information, not legal advice. Every case depends on its own facts.
Bureaus Must Follow Accuracy Rules
A credit bureau must follow reasonable procedures to assure the maximum possible accuracy of the information it reports about you. Putting another person’s information in your file may break that rule.
Bureaus Must Investigate
When you dispute an error, a credit bureau generally has 30 days to investigate, and up to 45 days in some cases.
Companies Can Be Held Accountable
When a bureau or a company that reports to it breaks these rules, you may be able to recover damages and attorney fees. What a case is worth depends on its facts, and no result is guaranteed.
Deadlines Apply
A claim generally has to be filed within two years of when you discover the violation, and no more than five years after it happened.
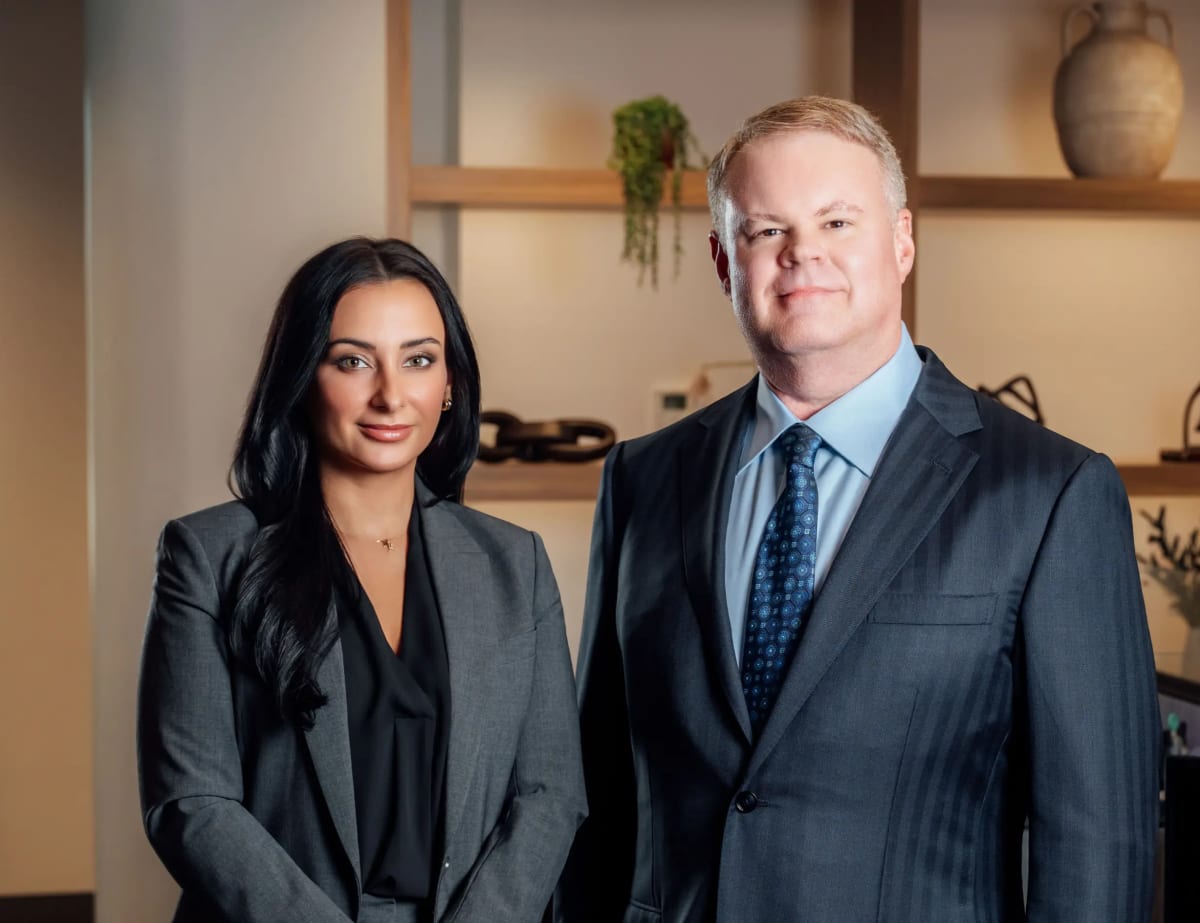
Think Your File Is Mixed?
Tell us what you found on your credit report. An attorney will tell you whether you may have a claim, and it costs you nothing to ask.
How It Works
What Happens After You Contact Us
Free Case Review
Tell us what you found. We look at your credit reports and any letters you received, and tell you whether you may have a claim.
We Build the Claim
We work out whose information was put in your file, who reported it, what the law required them to do, and what they failed to do.
We Press the Case
Most FCRA cases resolve without a trial. If yours does not, we can file in federal court. We keep you informed, and you decide whether to accept any offer.
You pay nothing out of pocket, and nothing at all unless we win.
Get a Free Case ReviewIn Their Own Words
Clients Who Came to Us With Errors on Their Credit
4.9 on Google, 33 reviews
“From the beginning, Raburn Kaufman was professional and attentive with my case. I paid no money out of pocket; they walked me through every step that I needed to take in order to present my case in the best way. Through any type of delay or setback, they always kept me updated with information.”
FabianIdentity Theft
“I am so grateful for all their patience and help to get through this case.”
AnitaInaccurate Credit Reporting
These are individual experiences. Prior results do not guarantee a similar outcome. Every case is different and must be evaluated on its own facts.
Our Team
The People Who Will Handle Your Case
A local Baton Rouge firm with national reach. Jonathan is frequently one of the first people a new client speaks with, and stays involved in every case from there.
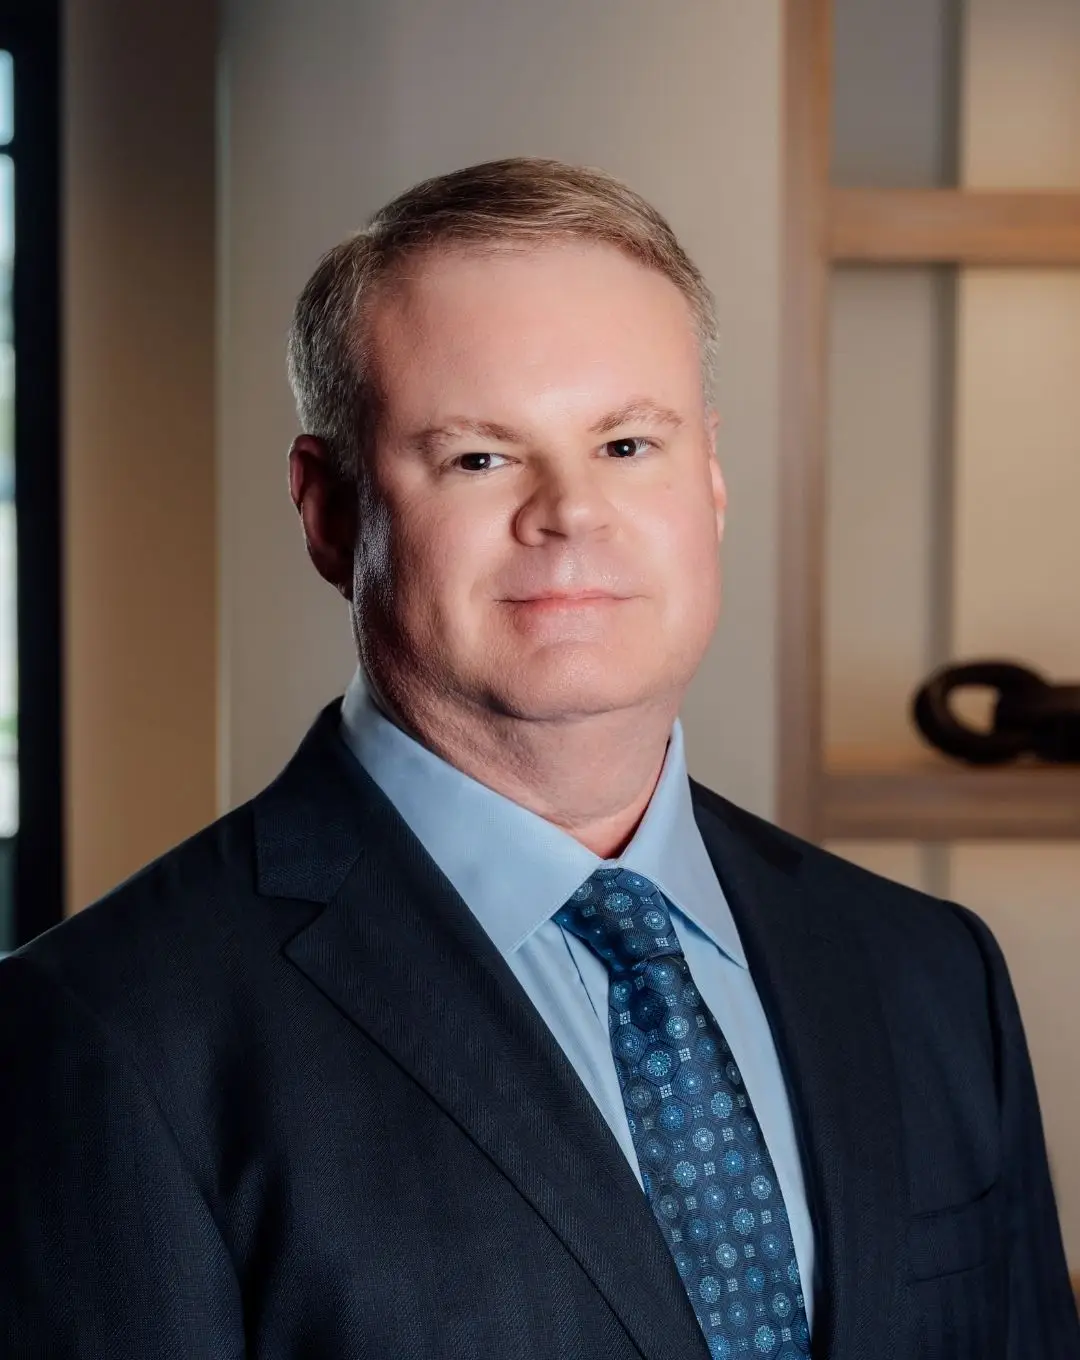
Jonathan Raburn
Managing Partner
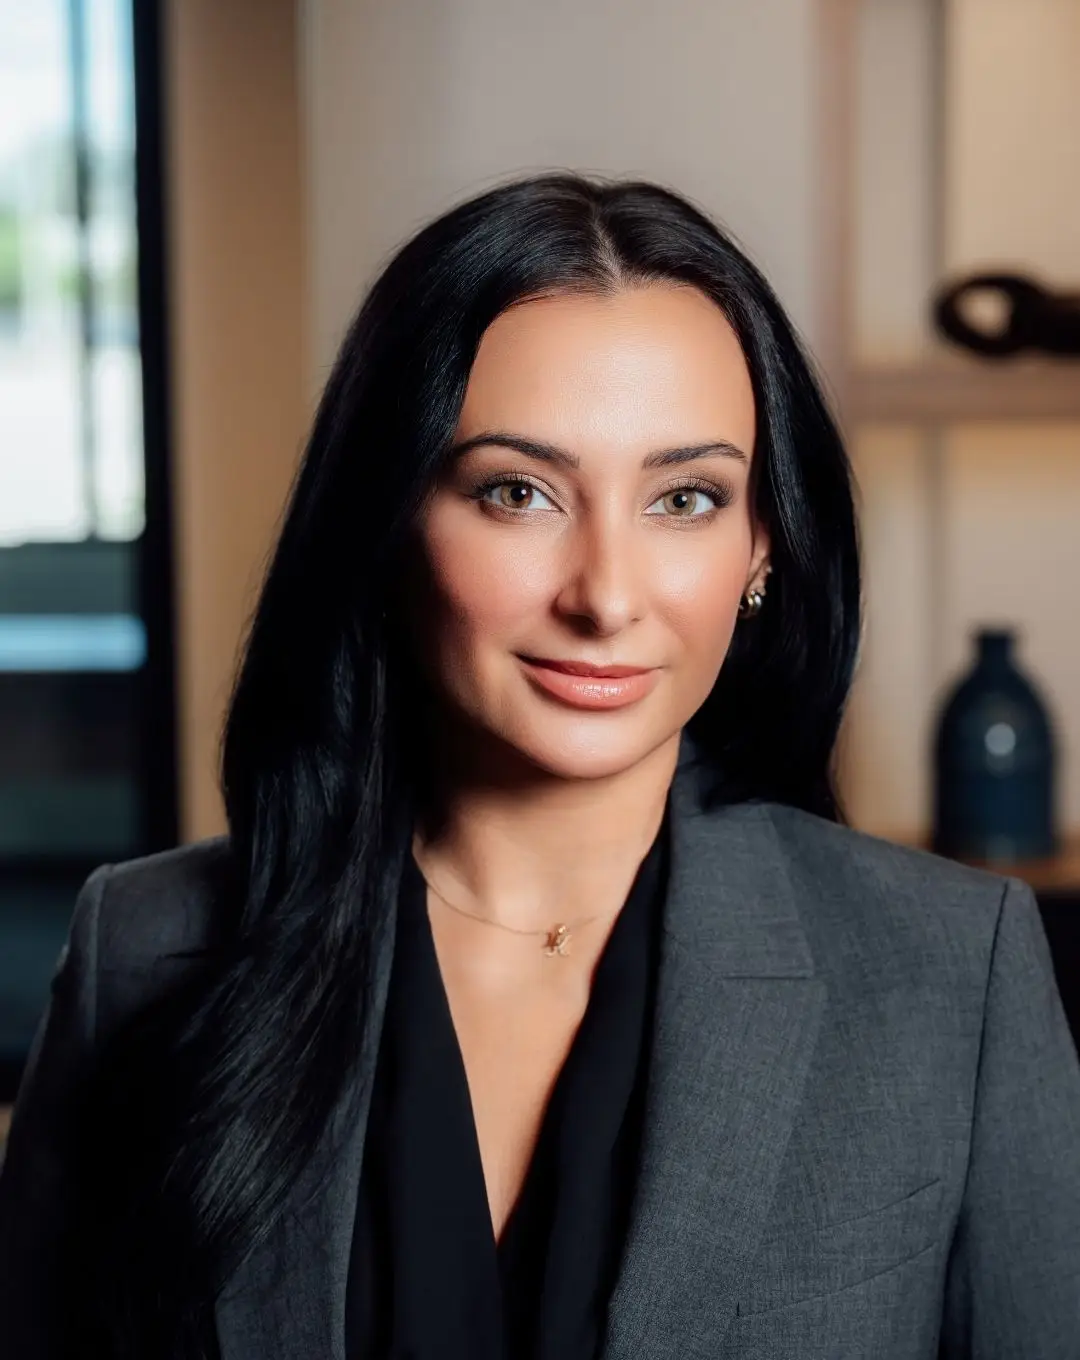
Kyle Kaufman
Partner
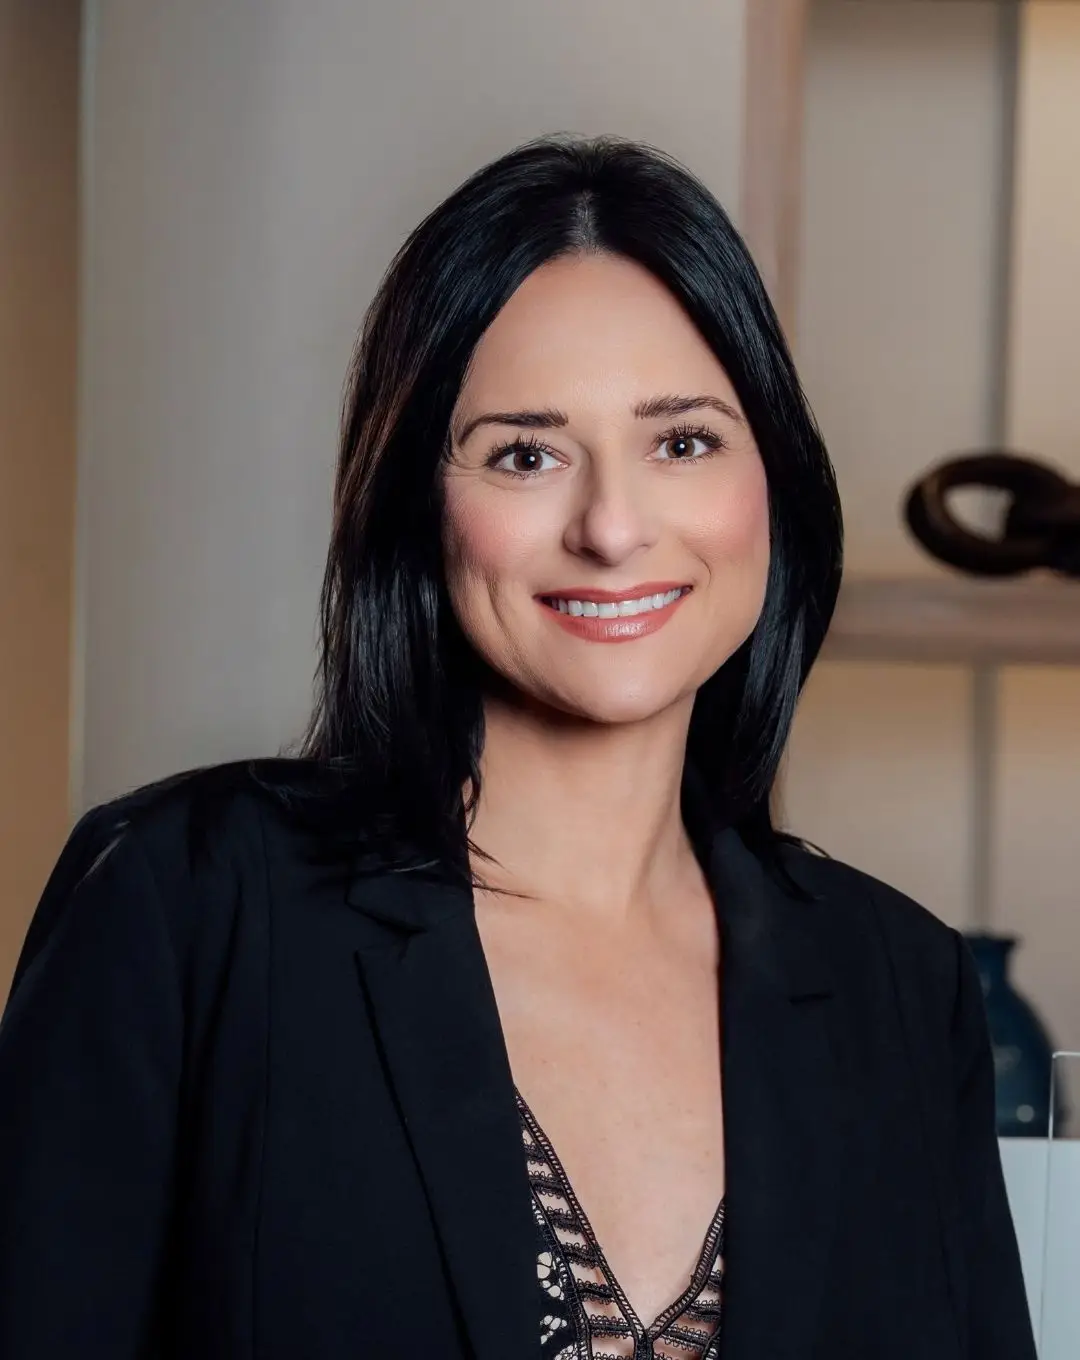
Andrae’ Melancon
Litigation Manager
Savannah Cooper
Pre-Litigation Manager
Questions
Common Questions About a Mixed Credit File
Are you a credit repair company?
No. We are a law firm. Our attorneys represent you under federal law, and when a credit bureau or a company will not correct its mistakes, we can file a lawsuit against it. We do not promise score increases, and we do not promise that accurate information will disappear.
What is a mixed credit file?
A mixed file happens when a credit bureau puts another person’s information in your file, such as their accounts, addresses, or Social Security number. It often starts with a similar name or other matching details. You did nothing wrong, and you can dispute the errors.
How is a mixed file different from identity theft?
With identity theft, someone used your information on purpose. With a mixed file, a credit bureau put another person’s information on your report by mistake, often because of a similar name or number. Either way you can dispute the errors, and an attorney can help work out which one you have.
I already disputed it. Why is it still there?
A bureau generally sends your dispute to the company that reported the account, and that company may answer that the information is correct. If the error is still on your report after a dispute, the bureau or the company may not have investigated properly. An attorney can look at what they did and what the law required.
What should I do first?
Get your credit reports from all three bureaus at AnnualCreditReport.com and mark every account, name, address, or number that is not yours. Dispute the errors in writing with each bureau that shows them, and with the company that reported them. Keep copies of everything you send and receive.
Do I have to pay anything?
No. You pay nothing out of pocket, and nothing at all unless we win. The case review is free.
Can I still bring a claim if it happened years ago?
Time limits apply. A claim generally has to be filed within two years of when you discover the violation, and no more than five years after it happened. Call soon, so an attorney can check your dates.
How long will my case take?
It depends on the facts and on how the bureau and the company respond. Some cases resolve without going to court, and others are filed in federal court. At your free review we will give you a realistic picture of what to expect.
Will this raise my credit score?
We cannot promise a score change. Our work is holding bureaus and companies accountable under the FCRA when they report inaccurate information, and getting the errors corrected is part of that.
Tell Us What You Found
A short form is all it takes. An attorney will review your details and get back to you.